
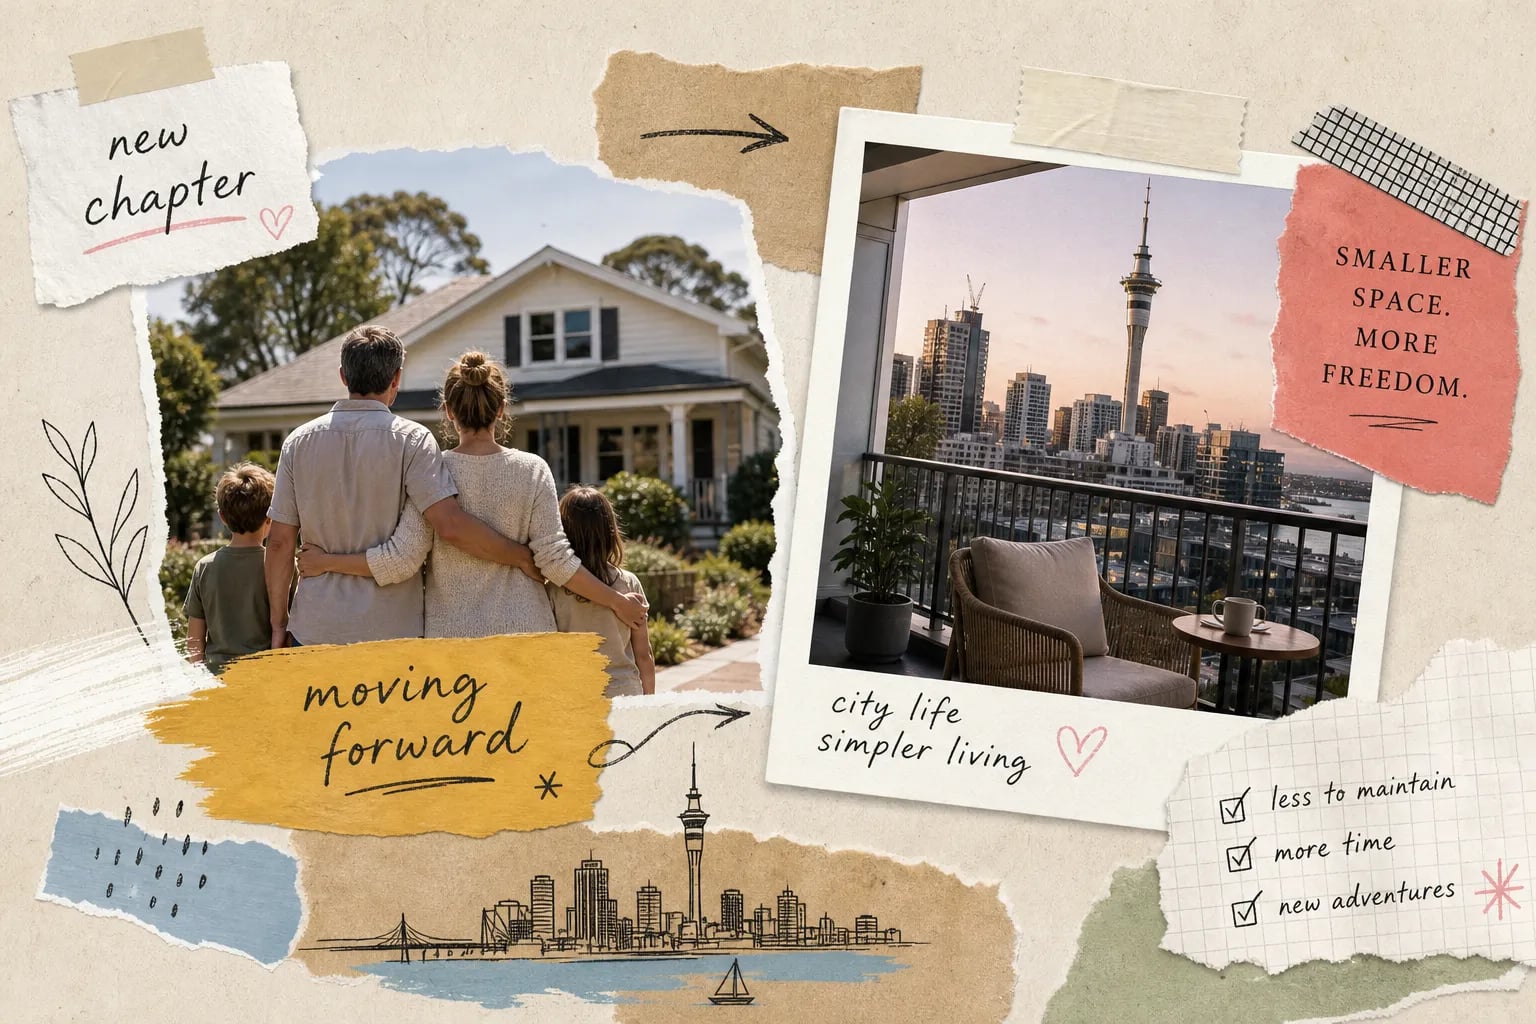
There's a moment that happens in a lot of Central Auckland homes. The kids have moved out, the third bedroom is now a gym nobody uses, and you're standing in the hallway thinking: "Why are we still mowing 600 square metres of lawn for two people?" It's not quite grief. It's not quite relief. It's more like a quiet reckoning with space you've outgrown.
If you're looking for guidance on selling a family home and buying an apartment in Auckland, you've come to the right place. It's one of the most emotionally loaded and logistically complex property moves a homeowner can make, whether you're downsizing to a unit or making a deliberate lifestyle shift to apartment living. You're running two transactions at once, navigating a different legal structure on the buy side, and making a lifestyle change that's as significant as the financial one. But here's the thing: it's also one of the most liberating moves available to you. Local agents who work Central Auckland every day can often identify buildings with remediation histories and emerging neighbourhood trends, guiding homeowners through exactly this transition regularly. Done in the right sequence, with the right professionals, it can be remarkably smooth.
Here's how to do it well.
Before you open a single apartment listing, your most important job is getting the family home into the strongest possible condition for market. This directly affects both your sale price and your timeline, which in turn determines what you can afford and when you can move.
Start with the basics: minor repairs, fresh paint, landscaping and a thorough de-clutter. These are the things buyers notice before they notice anything else. While sellers in New Zealand are not legally required to provide a LIM or building report, you do have a clear duty to disclose known material defects. Unconsented work, weathertightness issues, council notices, outstanding Code Compliance Certificates, and boundary disputes all fall into this category. Get a conveyancing lawyer involved four to six weeks before you plan to list; they'll review the title and consent records and flag anything that needs addressing before marketing begins.
Finding good trades on short notice is one of the biggest headaches in pre-sale preparation. Having access to a trusted network of painters, landscapers and electricians, the kind of connections that come from years of working in the same suburbs, can make a real difference. It's one of the practical advantages of working with Team Thompson, who offer sellers in Epsom and Mt Eden and central Auckland that kind of ready-made network, where good prep work can make a meaningful difference to the final sale price.
Budget realistically. Agent commission in Auckland typically runs 2.5% - 4% plus GST; a common tiered structure charges approximately 3.95% on the first $400,000 and 2% on the balance, plus GST. On a $1 million sale, that's roughly $31,970 including GST. Add a quality marketing campaign (NZ$3,500, $7,000), conveyancing fees (NZ$1,000, $2,500), staging if needed, and any mortgage break fees. The all-in cost most commonly lands between 3% and 5% of the sale price.
On timing: allow around three weeks of preparation before listing, then factor in a median listing-to-sale period of approximately 48 days based on mid-2026 data, followed by four to six weeks to settlement. From the day you list to cash in the bank, eight to sixteen weeks is a sensible planning assumption. Know this number before you start browsing apartments.
This is where most people feel the pressure spike. Running two transactions simultaneously requires a clear plan, not optimism. The sequence you choose has real downstream financial consequences, get it right and the whole transition flows; get it wrong and you're paying bridging interest you hadn't budgeted for.
Selling first gives you a confirmed budget and removes financial exposure, but it can leave you needing temporary accommodation between settlements. Buying first means a seamless move, but creates overlapping ownership and real financial risk if the family home takes longer to sell or achieves less than expected. Many experienced Auckland agents suggest selling first where possible, particularly when apartment supply in popular inner suburbs is reasonably consistent, though the right approach depends on your specific financial position and timeline.
There's also a third path worth understanding: simultaneous settlement negotiation, where both settlement dates are aligned so you move out and move in on the same day. This requires both transactions to be unconditional and tight lawyer-to-lawyer coordination. It's not always achievable, but when it works, it removes the gap entirely.
Bridging finance is an interest-only, short-term loan secured against both properties, used to fund the purchase before the sale settles. A closed bridge means your sale is already unconditional and you have a known settlement date; this is lower risk and easier to get approved. An open bridge means your property hasn't sold yet, which is riskier and attracts tighter lending criteria. As a rough planning figure, a $500,000 bridge at approximately 9% costs around $3,750 per month in interest before fees.
Lenders assess peak debt, end debt, your equity position (often requiring 30-35% equity post-transaction), and a credible plan to sell the existing property. Get written numbers from a mortgage broker before you commit to anything, not a ballpark figure, but actual monthly interest, peak debt, minimum acceptable sale price and end mortgage. If a rent-back arrangement from the buyer is possible (where you stay on as a tenant after settlement for an agreed period), that's another option worth exploring when timing is tight.
Now the part many buyers enjoy most, though it's also where expensive mistakes get made. Choosing the right apartment means thinking carefully about both lifestyle fit and building quality.
Ask yourself the practical questions: walkability to cafés and medical services, proximity to public transport, access to green space. Central Auckland suburbs like Parnell, Ponsonby, Grey Lynn, Newmarket and the CBD each offer apartment stock across a wide price range, with different character and different trade-offs. Two-bedroom apartments in these suburbs currently range from roughly NZ$600,000 in Newmarket to NZ$1.35 million in Ponsonby, depending on building quality and floor plan, figures that reflect mid-2026 sales and listing data for those areas.
Then there's the building era issue, which is non-negotiable to understand. Apartments built roughly before 2004 carry a higher weathertightness risk due to the leaky-building period of construction. Monolithic cladding, flat roofs, balconies without proper drainage, these are warning signs worth investigating carefully. Pre-2004 buildings aren't automatically problems, but due diligence costs more and takes longer. Build this into your offer timeline from the start.
Also, consider whether an apartment is going to accommodate your pets. Not all properties are suitable and this can be a big consideration. After all pets are part of the family too.
New builds offer lower maintenance risk and sometimes a builder's warranty, but can come with higher body corporate levies, smaller floor plans and limited character. Established buildings in inner Auckland often offer larger living areas and more settled communities, but require careful scrutiny of the building's history and financial health. The right building is one where the numbers and the condition match up honestly, and confirming that means digging into documents most buyers never think to request.
Unit title apartments have a different legal and financial structure to freehold homes. Missing one document here can cost you tens of thousands after settlement.
Your annual body corporate levy covers shared costs: building insurance, cleaning, utilities for common areas, administration and routine maintenance. A separate contribution funds the long-term maintenance reserve for major future work. For a typical Central Auckland mid-rise, budget approximately NZ$4,000, $8,000 per year in levies, with NZ$5,000, $6,500 a reasonable working estimate. A special levy is an additional charge for urgent or major work, and a low current levy can mask an under-funded reserve, meaning a large special levy may be coming.
Always request the last three years of financial statements, AGM minutes and the long-term maintenance plan. Read the minutes carefully. Repeated references to "water ingress," deferred maintenance, increasing insurance premiums or proposed borrowing are red flags. Have your lawyer review the statutory pre-contract disclosure statement before going unconditional, not after. Allow three to five working days for a straightforward review; more complex buildings need ten or more.
A standard pre-purchase building report for an apartment should cover the unit and accessible common areas, including cladding, balconies, roof, wet areas and moisture readings. Costs typically range from NZ$400, $1,500 depending on scope. Where the building has plaster cladding, staining, balcony junctions or a pre-2004 build date, commission a specialist weathertightness assessment on top. Also check whether the building has an earthquake-prone building notice with Auckland Council; any required structural strengthening programme becomes a shared cost through the body corporate.
Order the Auckland Council LIM (NZ$ 387 standard or NZ$ 522 for urgent) and compare the consented layout to what's actually built. Make your offer conditional on satisfactory review of the LIM, title, building report, weathertightness assessment and body corporate documents, with enough time to get the specialist reports back before you go unconditional.
No one should attempt a dual-transaction property move without an experienced team working alongside them. The professionals you choose will either compress your stress or compound it.
A mortgage broker who works regularly with Auckland buyers will know which lenders are comfortable with bridging scenarios, what equity thresholds each bank applies and how to structure the application cleanly. Get written figures before committing: peak debt, monthly bridge interest, minimum acceptable sale price and final end mortgage. Your conveyancing lawyer handles both sale-and-purchase agreements, the LIM review, title and consent checks, and unit-title disclosure requirements. Pre-contract disclosure must be given before the buyer signs; pre-settlement disclosure must be provided at least five working days before settlement. Settlement day mechanics, where funds flow correctly across two transactions simultaneously, require lawyer-to-lawyer coordination that only works when everyone is prepared well in advance.
Selling a family home while buying an apartment isn't a simple two-step. It requires a local agent who understands both Central Auckland's established suburbs and its apartment market, who gives you a realistic appraisal rather than an inflated one to win the listing, and who can connect you to the right broker, lawyer and tradespeople without you having to start from scratch. Deborah and Robert Thompson at Team Thompson bring exactly this kind of local knowledge to the transition. We operate under the Barfoot & Thompson umbrella with solid experience in Auckland's body corporate landscape and the professional relationships to help coordinate the full journey from pre-sale preparation to settlement day.
The physical move gets overlooked until the last minute more often than you'd think. Plan it early and build in a buffer.
If your family home settles before the apartment does, you have three options. First, negotiate a rent-back with the buyer, staying on as a tenant for an agreed period at market rent, with a formal agreement reviewed by your lawyer. Second, work through both sets of lawyers to align settlement dates. Third, move into short-term accommodation. In Central Auckland, temporary furnished accommodation currently runs approximately NZ$700, $950 per week for a two-bedroom apartment, plus storage costs of NZ$ 150-$ 400 per month, bond, and removal fees. Building a four to six week buffer into your plan is sensible; settlement dates do slip, and a contingency prevents one delay from unravelling everything.
Handing over the keys to the family home is genuinely emotional. That feeling doesn't mean you've made the wrong call. The homeowners who thrive in apartment living are those who have made an active choice about what they're moving toward: a lower-maintenance lifestyle, a central location, and often the financial freedom that comes with releasing equity from a large family property. You're allowed to feel the loss and embrace the gain at the same time. In fact, the ones who do both tend to settle into their new life faster.
Selling the family home and buying an Auckland apartment simultaneously is genuinely complex, but it's also a well-worn path. The four moves that make it work: prepare the family home early, sort the timing and finance structure before you commit to a purchase, do thorough apartment due diligence with a focus on body corporate health and building condition, and surround yourself with professionals who have done this before. For proper guidance on selling a family home and buying an apartment in Auckland, whether you're downsizing to a unit or simply ready for a change of pace, getting the sequence right from the start is what makes the difference.
If you're starting to think seriously about making the move, get in touch with Deborah and Robert at Team Thompson for a free, no-obligation property appraisal and a straightforward conversation about how to sequence the whole transition in a way that fits your timeline.
There's no pressure and no guesswork, just two local agents who know this market well and genuinely enjoy helping people get the next chapter right.